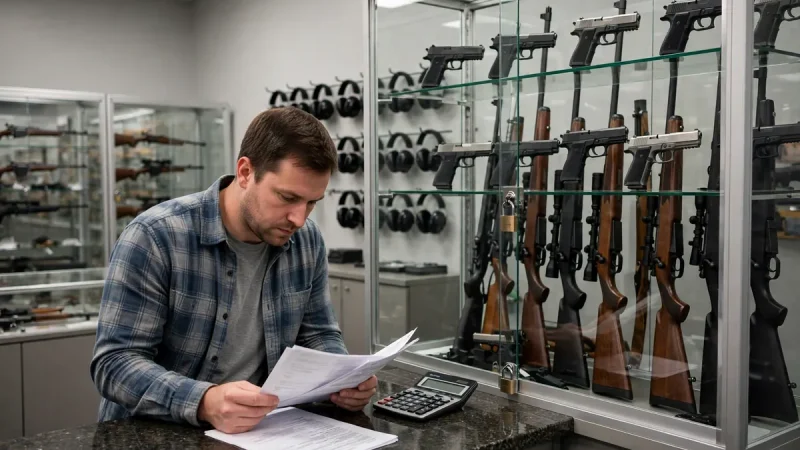

You found the firearm you want, and then reality taps your shoulder. The price fits your long-term budget, but not this month’s cash. Sound familiar to you as a careful, lawful buyer? Flexstar gun financing is one name shoppers may see during that search. This playbook explains firearm financing calmly, legally, and without hype. No promises live here, just total-cost thinking and careful questions. Read every term yourself, because signatures outlast sales excitement.
Step One — Separate the Purchase From the Financing
Two decisions hide inside every financed firearm purchase, actually. You choose a specific firearm from a licensed dealer first. Separately, you choose how to pay over time responsibly. Mixing those decisions, however, clouds both judgments at once. A desirable model can make weak credit terms look acceptable. Clear separation, therefore, protects your wallet and your standards.
Licensed dealers sit at the center of lawful firearm sales. Federal law requires licensed dealers for most commercial firearm transactions. Background checks and transfer paperwork follow applicable federal and state law. Financing, notably, never replaces or bypasses those legal steps. Any offer suggesting otherwise deserves immediate, serious suspicion from buyers. Walk away, consequently, whenever legality sounds optional or vague.
Step Two — Understand How Retail Financing Usually Works
Retail financing typically involves a lender, dealer, and buyer together. The dealer sells the firearm through normal legal channels. A lender or finance partner, meanwhile, pays or credits the purchase amount. You then repay that amount over an agreed period. Interest, fees, and conditions depend entirely on your signed agreement. Generic guides, therefore, can explain structure but never your terms.
Some arrangements resemble installment loans with fixed repayment schedules. Others function more like revolving credit for future purchases. Each structure, notably, handles interest and late payments differently. Ask which model applies before discussing monthly payment amounts. The monthly figure alone, consequently, hides the true total cost. Smart buyers, instead, start with total repayment and work backwards.
Step Three — Calculate the Real Total Cost
Total cost means every dollar you repay over time. Principal, interest, and any fees all belong in that number. Ask for the full repayment figure in writing upfront. Then compare that figure against the cash purchase price directly. The difference shows exactly what spreading payments costs you. Sometimes that convenience feels worthwhile, and sometimes it clearly does not.
Time changes the math more than many buyers expect. Longer repayment periods usually lower each monthly payment amount. However, longer periods can also raise total interest paid overall. Shorter periods demand more monthly discipline from your budget instead. Run both scenarios on paper before choosing either one. Our guide to Navitas financing options explains similar total-cost thinking generally. Numbers, notably, stay honest when you write them down.
- Write the cash price and financed total side by side.
- Ask about every fee in plain language first.
- Compare a shorter and longer repayment scenario carefully.
- Check early repayment rules before signing anything.
- Keep the signed agreement with your purchase records.
Step Four — Read These Terms Before You Sign
Interest terms deserve your slowest, most careful reading session. Is the rate fixed, variable, or promotional for a period? When does any promotional period end for your account specifically? What happens after that date under the written agreement terms? Verbal summaries, meanwhile, cannot override the document you sign. Read the actual pages, consequently, even when the print feels tedious.
Fees and penalties form the second critical reading block. Late fees, returned-payment fees, and account charges may all apply. Ask how grace periods work under your specific agreement terms. Similarly, ask whether early repayment carries any penalty at all. Equipment buyers face parallel questions in our Northmill equipment finance guide for businesses. Diligence, notably, transfers across every financing category and purchase.
Default and repossession language also matters, however uncomfortable it feels. What happens if you miss payments during a hard month? Which notices does the lender send before further action begins? Can the account affect your credit reports over time? Honest answers now prevent panic and confusion later on. Responsible lenders, consequently, explain hard scenarios without dodging them.
Step Five — Protect the Legal Side of the Purchase
Financing never changes who may legally buy a firearm. Federal and state eligibility rules apply to the buyer personally. Background check processes run through the licensed dealer as required. Waiting periods and permit rules vary significantly by state today. Therefore, confirm your state’s current rules through official sources directly. Dealer staff, notably, handle transfers daily and know local process.
Straw purchase warnings deserve plain emphasis for every reader. Buying a firearm for someone who cannot legally buy one is illegal. Financing paperwork in your name makes that danger even clearer. Never sign credit documents connected to another person’s firearm purchase casually. Relationship pressure, meanwhile, never excuses unlawful transfer arrangements at all. Protect yourself, consequently, by keeping purchases personal and lawful.
Safe storage belongs in the same responsible ownership conversation. Budget for a proper safe or lock alongside the firearm itself. Our guide to cheap ways to improve home security covers wider household protection basics. Storage laws also vary, so check your state rules officially. Responsible financing, notably, includes the full ownership cost picture.
Step Six — Budget Beyond the Monthly Payment
Ownership costs continue long after the first payment clears. Ammunition, range time, training, and maintenance all cost money regularly. Insurance considerations may also apply for some owners and collections. Cleaning supplies and safe storage add smaller recurring expenses too. Hence, your monthly budget should carry the whole ownership picture. Payment-only budgeting, consequently, creates strain within a few months.
Training deserves a deliberate line in that ownership budget. Professional instruction builds safe habits and genuine shooting competence steadily. Many new owners, notably, underfund training while overfunding accessories. Reverse that instinct whenever your budget forces hard choices. Skill and safety, after all, protect everyone around you. Our wider money guidance in the digital payment wallet guide reinforces tracking every cost. Visibility, therefore, keeps small expenses from surprising you later.
How Does Financing Compare With Saving Up?
Saving first remains the cheapest route for most buyers honestly. Cash purchases avoid interest and most financing fees entirely. Waiting, however, tests patience when a specific model appears briefly. Some buyers use layaway arrangements through dealers instead of credit. Each option, notably, carries different timing and flexibility trade-offs. Compare all three paths before defaulting to instant financing.
Credit cards form another comparison point for disciplined buyers. Card terms, limits, and rewards differ wildly between individual accounts. Dealer policies on card payments also vary by business. Therefore, compare total costs across methods with real written figures. Sentiment and habit, meanwhile, make poor financial calculators for anyone. The cheapest lawful path, consequently, wins on paper every time.
What Questions Should You Ask the Dealer?
Dealers answer financing questions daily, so ask yours without embarrassment. Which lender or partner provides this financing program exactly? Can you review the full agreement before committing to anything? Who services the account if billing questions arise later on? Which fees come from the lender versus the dealer separately? Clear ownership of each answer, notably, prevents future finger-pointing.
Ask also about returns, defects, and financing interactions carefully. A returned or repaired firearm may not pause your payments automatically. Warranty handling follows manufacturer and dealer policies in most cases. Your loan obligation, meanwhile, usually continues under its own agreement. Knowing that separation upfront prevents a painful double surprise later. Written policies, consequently, deserve a folder in your records.
- Who is the actual lender behind this program?
- Can I read the complete agreement at home first?
- What is my total repayment amount in writing?
- Does early repayment reduce my total cost here?
- Who do I call about billing problems later?
Red Flags That Should Slow You Down
Pressure tactics signal a deal that cannot survive scrutiny. Sign today language, notably, serves the seller and not you. Promises of guaranteed approval also deserve deep, immediate skepticism. Legitimate lenders review applications and publish real eligibility conditions. Vague answers about total cost form another serious warning sign. Trustworthy partners, consequently, welcome calculators, questions, and overnight thinking.
Unclear legal talk forms the brightest red flag here. Anyone minimizing background checks or paperwork should end the conversation. Similarly, anyone suggesting another person sign for you is dangerous. Leave that business and report concerns through appropriate official channels. Lawful dealers, meanwhile, protect their licenses by following every rule. That strictness, notably, protects buyers as much as sellers.
What If Your Budget Says Not Yet?
Sometimes the honest playbook ends with a patient pause. Waiting lets you save, compare dealers, and strengthen your finances. Prices and availability change, yet your financial stability matters more. A smaller first purchase may also fit your real needs better. Many experienced owners, notably, started modestly and upgraded years later. Patience, consequently, builds collections without building stressful debt.
Use the waiting period productively rather than just browsing listings. Take a safety course and rent range time for experience. Hands-on trials reveal grip, caliber, and purpose preferences clearly. Insurance planning also fits this season, as our NWA insurance guide discusses generally. Preparation, therefore, turns a delayed purchase into a smarter one. Legal knowledge in our legal rights guide shows similar preparation value elsewhere. Knowledge, in short, compounds quietly before money ever moves.
How Does Your Credit History Shape Your Options?
Lenders review credit history when evaluating most financing applications. Payment history, existing debts, and income stability all influence decisions. Approval, notably, is never automatic or guaranteed for any applicant. Some applicants receive different terms based on that review process. Others may receive a denial with an explanation letter afterward. Understanding that reality beforehand, consequently, keeps expectations calm and grounded.
Preparation improves your position before any application reaches a lender. Review your credit reports for errors through official channels yearly. Paying down revolving balances can also strengthen your overall profile gradually. Avoid opening several new credit accounts in one short season. Each application, meanwhile, can leave an inquiry on your record. A cleaner file, therefore, usually supports calmer financing conversations.
What Should First-Time Buyers Do Differently?
First-time buyers juggle financing, paperwork, and unfamiliar terminology simultaneously. Slow the process down deliberately, because nobody benefits from rushing you. Bring a written question list to the dealership visit itself. Ask staff to explain each form before you sign it. Reputable dealers, notably, explain background check steps patiently and clearly. Confusion, consequently, is a signal to pause, not sign.
Purpose clarity also protects first-time buyers from overspending early. Define whether the firearm serves sport, hunting, or home purposes primarily. That answer shapes model, caliber, and accessory needs significantly. Training providers can advise beginners before a purchase happens too. A modest, well-matched first purchase often teaches more than excess. Mentors, in short, help budgets and skills grow together.
How Should You Keep Records After the Purchase?
Records protect you long after excitement fades at home. Keep purchase receipts, financing agreements, and warranty papers together safely. Store copies digitally with clear file names and backup protection. Serial number records also help with insurance or theft reports. Never store sensitive documents casually in shared or public folders. Organization, notably, turns stressful moments into manageable paperwork tasks.
Payment records deserve the same disciplined treatment every month. Confirm each payment posts correctly and on schedule always. Report discrepancies to the servicer promptly with dates documented. Keep final payoff confirmation after the last payment clears fully. That document, consequently, closes the financing chapter with proof. Future purchases, meanwhile, become easier with a clean history.
Your Firearm Financing Playbook Checklist
- Choose the firearm and dealer on merit first.
- Demand the total repayment figure in writing.
- Read interest, fee, and default terms fully.
- Follow every federal and state legal step.
- Budget training, storage, and ownership costs too.
Flexstar gun financing, like any financing, is simply a tool. Tools serve careful hands and punish rushed signatures badly. Separate the purchase from the credit, calculate totals, and read everything. Keep every step lawful, licensed, and fully documented throughout. Then buy only what your complete budget genuinely supports. That discipline, finally, unlocks ownership without unlocking regret.